Blogs
Reverse Mortgage for Home Repairs in Canada
Reverse Mortgage, Home Repairs, Canadian Seniors
Using a Reverse Mortgage for Major Home Repairs in Canada: A Practical Guide for Homeowners 55+
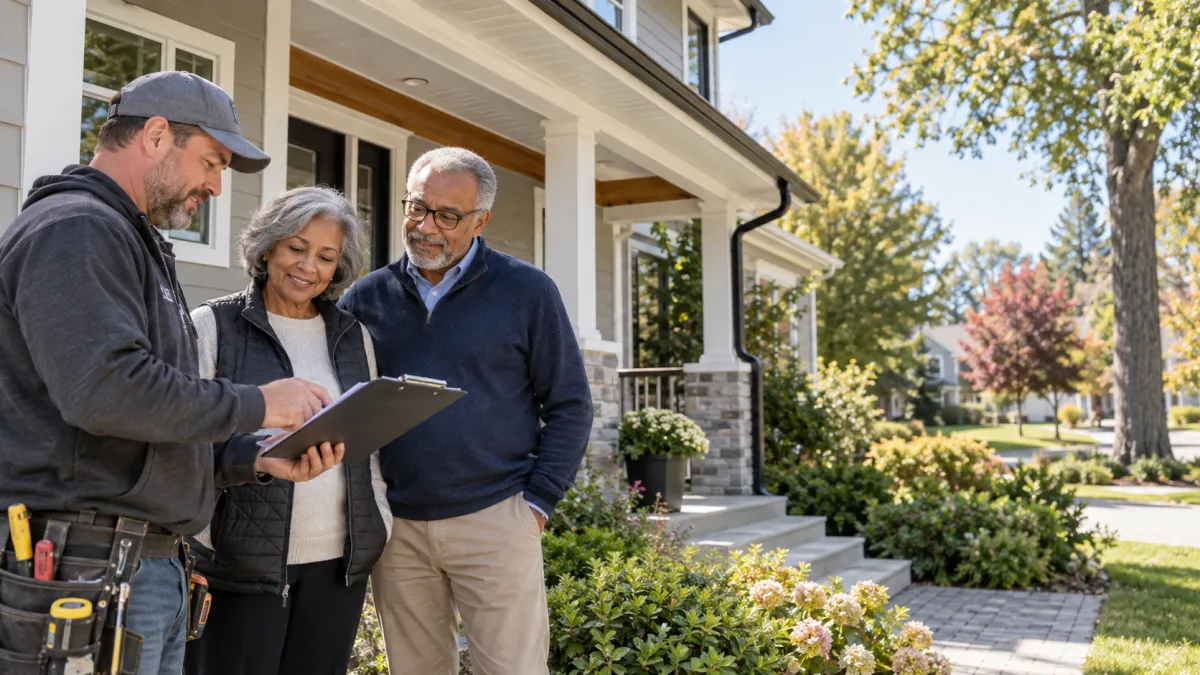
If you are 55 or older and facing a big repair like a leaking roof, failing furnace, aging plumbing, foundation cracks or cold drafts, it can feel overwhelming. You want to stay in the home you love, but you may not want – or be able – to take on traditional debt or dip heavily into savings. A reverse mortgage is one option that can help cover major repairs so you can remain safely and comfortably at home, but it comes with important responsibilities and trade-offs. This guide walks you through how it works in Canada, how to plan your projects, and how to decide if it is right for you.
Why Major Repairs Matter for Staying Safely at Home
Many Canadian homes owned by people 55+ were built decades ago. Time, weather and changing building standards mean key systems eventually need more than small fixes. Putting off repairs can raise safety risks and costs down the road. For example:
A worn roof can lead to leaks, mould and structural damage that is far more expensive than replacing shingles early on.
An old furnace or boiler can fail during a cold snap, putting your health at risk and leaving you scrambling for emergency service at premium prices.
Outdated plumbing or deteriorating foundations can cause floods, cracks and uneven floors that are harder to repair once damage spreads.
Across Canada, a new asphalt roof for a typical detached home can cost in the tens of thousands of dollars, while furnace replacement, foundation work or major plumbing upgrades can easily run into the thousands or tens of thousands. For many retired homeowners, those amounts are not sitting in a chequing account. That is where financing, including reverse mortgages, may come in.
Step One: Prioritizing Your Repair Projects
Before you look at any type of financing, it helps to be clear on what actually needs to be done, and in what order. A simple way to think about prioritizing is to group projects into three buckets: safety, structure and comfort.
Safety and health first. Anything that could directly affect your health or basic living conditions should move to the top of the list. This includes heating systems, electrical hazards, serious leaks, mould, or anything that could lead to a fire, flood or loss of heat in winter.
Structure and weatherproofing next. Roofs, foundations, windows, doors and exterior walls protect your home from the elements and keep it solid. If these fail, other parts of the house can quickly be damaged, and repair costs can grow quickly.
Comfort and accessibility after that. Once safety and structure are under control, you can look at projects that improve day‑to‑day comfort and help you age in place, like better insulation, bathroom grab bars, walk‑in showers or improved lighting.
A trusted contractor, home inspector or building technologist can help you create a written list of issues, with rough timelines. This plan becomes the foundation for deciding whether a reverse mortgage, or another option, makes sense for you.
Getting and Comparing Contractor Quotes the Smart Way
Reliable quotes are essential before you decide how much money you might need. For major repairs, aim to get at least two, and ideally three, written quotes from reputable contractors who are properly licensed and insured in your province or territory.
Ask each contractor to spell out exactly what is included: materials, labour, permits, disposal, and any warranty on workmanship or products.
Check references, online reviews and, where possible, ratings from Canadian sites that track homeowner experiences with trades.
Be cautious about quotes that are far lower than others. They may be using lower‑grade materials or underestimating the scope of work.
For older homes, it is wise to build in a contingency – often 15% to 25% of the project cost – for surprises behind walls or under floors. When you are thinking about a reverse mortgage amount, it is better to plan for realistic, fully‑loaded costs than to come up short mid‑project.
How Reverse Mortgages Work in Canada
A reverse mortgage is a loan that lets you access some of the equity in your home without having to sell or make regular monthly payments. In Canada, reverse mortgages are designed for homeowners 55 and older and are regulated under federal and provincial rules. The Financial Consumer Agency of Canada (FCAC) explains that you can usually borrow up to a percentage of your home’s value, often up to about 55%, depending on your age, home value and location. The funds you receive do not affect Old Age Security (OAS) or Guaranteed Income Supplement (GIS) benefits, because they are considered loan advances, not income (source: Government of Canada, FCAC).
Instead of making monthly payments, interest is added to the balance you owe. The loan is usually repaid when you sell your home, move out permanently, or when the last borrower passes away. Reverse mortgages offered by federally regulated lenders are generally non‑recourse, which means that as long as you meet your obligations, you or your estate will not owe more than the fair market value of the home when it is sold, even if housing prices fall. Lenders follow rules set by the Office of the Superintendent of Financial Institutions (OSFI) to keep loan‑to‑value ratios and underwriting practices conservative.
Eligibility for a Reverse Mortgage in Canada
While each lender has its own guidelines, some common eligibility points across Canada include (sources: FCAC, major Canadian reverse mortgage providers):
Age. You must be at least 55 years old. If you apply with a spouse or partner who is on title, both of you must meet the minimum age requirement.
Home ownership and equity. You must own your home and have a meaningful amount of equity. The more equity you have and the older you are, the more you may be able to borrow, up to the lender’s maximum percentage of your home’s value.
Primary residence. The property must be your principal residence, generally occupied for at least six months of the year. Vacation homes and most rental properties do not qualify.
Property type and location. Detached homes, townhomes and many condominiums may qualify, subject to lender rules and local market conditions. Some rural or remote properties may have limits or may not be eligible with certain lenders.
Unlike a traditional mortgage, your income and credit score often play a smaller role, because you are not expected to make regular payments. However, lenders still want to be confident that you can keep up with property‑related expenses such as taxes, insurance and basic maintenance.
Your Ongoing Obligations as a Homeowner with a Reverse Mortgage
Taking out a reverse mortgage does not change the fact that you are a homeowner. You keep the title to your home, and you also keep the responsibilities that come with it. To stay in good standing with your lender, you are typically required to:
Live in the home as your primary residence, according to the lender’s occupancy rules.
Keep property taxes and home insurance up to date. Falling behind on these can put you in default, even if you have never missed a payment on any other loan in your life.
Maintain the property in reasonable condition. Major neglect can affect the home’s value and may be considered a breach of the mortgage terms.
In some provinces, such as Ontario, brokers are required to ensure you receive independent legal advice before you sign a reverse mortgage, and your lawyer must confirm this in writing. This is for your protection and gives you space to ask questions in a setting that is focused only on your interests.
Costs, Fees and How Compounding Interest Affects Your Equity
Like any mortgage product, a reverse mortgage comes with costs. It is important to understand these clearly before you proceed. While exact amounts vary by lender and province, you may see:
Application or setup fees for arranging the loan.
Appraisal fees to determine your home’s current market value.
Legal fees for your own lawyer and the lender’s legal work at closing.
Possible prepayment penalties if you choose to pay off the loan early, depending on the timing and lender policy.
The most important cost, however, is the interest that builds up over time. Because you are not making regular payments, interest is added to the balance you owe, and then future interest is charged on that higher balance. This is called compounding interest. Over a number of years, compounding can significantly increase the total amount you owe and reduce the equity left in your home for future needs or for your estate.
For example, if you borrow a lump sum to replace your roof and upgrade your heating system, the amount you owe will grow each year as interest is added. If your home’s value also rises over time, you may still have equity left when the loan is repaid. But if property values are flat or fall, or if you keep borrowing more, your remaining equity will be smaller. This is not necessarily a problem if your priority is to stay safely in your home, but it is something to consider carefully, especially if you hope to leave a large inheritance tied to the property.
Using a Reverse Mortgage Specifically for Major Home Repairs
Many Canadian homeowners use reverse mortgage funds for exactly the kinds of repairs you may be facing: roof replacement, furnace or boiler upgrades, electrical and plumbing work, foundation repairs, insulation, new windows and doors, or accessibility renovations such as walk‑in showers and ramps. Lenders will usually ask what you intend to use the funds for, and they may look favourably on projects that help maintain or improve the home’s condition and value.
You can often choose to receive the money as a lump sum, in regular advances, or a mix of both. For a defined repair project with signed quotes, a lump sum may make sense. For ongoing smaller improvements or contingency funds, a combination of an initial amount plus a reserve may be more comfortable. A knowledgeable mortgage broker can help you structure the funds in a way that lines up with your repair schedule and your comfort level.
Alternatives to Using a Reverse Mortgage for Repairs
A reverse mortgage is one tool, not the only one. Before you decide, it is wise to compare it with other options, such as:
Home equity line of credit (HELOC) or conventional refinance. These may offer different interest structures but usually require regular payments and stronger income qualification. If you are still working or have strong pension income, they may be worth exploring.
Government grants and programs. Depending on your province, income and the type of work, there may be home repair or accessibility grants, low‑interest loans or property tax relief programs for seniors. These can sometimes be combined with other financing to reduce how much you need to borrow privately.
Family support. Some families choose to treat help with repairs as an early inheritance or joint investment in the home. Clear communication and, ideally, written agreements help avoid misunderstandings later.
Selling and downsizing. For some homeowners, selling a larger or older home and moving to a smaller, lower‑maintenance property is the most practical long‑term solution. This can free up equity without taking on new debt, but it also means leaving a familiar place and neighbourhood.
Looking at these alternatives side by side with a reverse mortgage can help you feel more confident that you are choosing the path that truly fits your situation and values.
A Practical Checklist Before You Decide
To bring everything together, here is a simple checklist you can work through at your own pace:
List all current and expected repairs for the next 5–10 years (roof, heating, plumbing, foundation, windows, accessibility).
Rank them by safety, structural importance and comfort.
Get at least two written contractor quotes for each major project and include a 15–25% contingency in your budget.
Estimate your total funding need, including taxes, permits and temporary accommodation if required for major work.
Review your current mortgage balance (if any) and your home’s approximate market value to understand your equity position.
Explore all options: reverse mortgage, HELOC, traditional refinance, grants, family support, or downsizing.
Speak with a qualified mortgage broker who understands reverse mortgages and works with Canadian lenders, and ask them to provide clear written illustrations of how your loan balance and home equity could change over time under different scenarios.
Book an appointment with an independent lawyer to review the documents and explain your rights and obligations.
Questions to Ask a Mortgage Broker About Using a Reverse Mortgage for Repairs
A good broker will welcome your questions and take the time to answer them clearly. Here are some to consider bringing to your meeting or phone call:
Based on my age, home value and location, how much could I realistically qualify for, and how would that change if I chose a smaller amount just to cover essential repairs?
What are all the upfront and ongoing costs and fees I should expect, including legal, appraisal and any potential prepayment charges?
Can you show me written projections of how my loan balance and estimated home equity might look in 5, 10 and 15 years under different interest and housing market conditions?
What happens if I decide to sell and move in a few years? How is the reverse mortgage repaid, and what costs would apply at that time?
How will this reverse mortgage affect my spouse or partner if they outlive me, or if one of us needs to move into care while the other remains at home?
Are there any provincial rules or protections I should know about in my area, and how will you make sure I receive independent legal advice?
Frequently Asked Questions About Reverse Mortgages and Home Repairs
Will a reverse mortgage affect my OAS or GIS? According to the Financial Consumer Agency of Canada, reverse mortgage advances are loan funds, not income, so they do not affect Old Age Security or Guaranteed Income Supplement benefits. However, other sources of income or investments might, so it is always sensible to speak with a financial planner if you are unsure.
Can I use a reverse mortgage to repair a rental property? In most cases, no. Reverse mortgages in Canada are usually limited to your primary residence. Some lenders may have specific exceptions, but generally, rental and vacation properties do not qualify.
What if I change my mind after I apply? Lenders and provincial regulations may provide a short cooling‑off period, and you may be able to cancel before funds are advanced. Once the loan is in place, you can usually repay it, but there may be prepayment charges. Your lawyer and broker can explain the timelines and costs that apply in your situation before you sign anything.
Can I still leave an inheritance if I use a reverse mortgage? Many homeowners who use reverse mortgages still leave an inheritance, but the amount may be smaller because the loan balance grows over time. The outcome depends on how much you borrow, how long you keep the loan, the interest that accumulates and how your home’s value changes. Your broker can show you scenarios so you can see the potential impact on your estate.
Is a reverse mortgage right for everyone? No. It can be a helpful tool for some homeowners, especially those who want to stay in their home for the long term and value comfort and safety over leaving maximum equity. For others, a different approach – such as a smaller home, a HELOC, or help from family – may be a better fit. The key is to take the time to understand your choices and not feel rushed.
A No‑Pressure Invitation from Rossander to Explore Your Options
Major repairs like a new roof, updated heating system, plumbing upgrades or foundation work are not just “nice to have.” They are central to your comfort, safety and ability to remain in the home and community you know. At the same time, using your home equity is a serious decision that deserves calm, careful thought.
At Rossander, our role is not to push you toward a reverse mortgage, or any other product. It is to listen, help you clarify your priorities, explain your options in plain language and give you the space you need to decide what feels right. If that means a reverse mortgage to fund essential repairs, we will walk you through the details. If another approach looks better, we will say so, and help you explore that path instead.
You are welcome to reach out for a conversation with no obligation and no pressure. Bring your questions, your contractor quotes and your concerns about the future. Together, we can look at how to keep your home safe, warm and comfortable – on terms that respect both your finances and your peace of mind.

Frequently Asked Questions
Do mortgage brokers actually get better rates?
Often, yes. Brokers have access to rates from multiple lenders, including some not available directly to consumers, and can compare them to find competitive options for your situation.
Will talking to a mortgage broker hurt my credit score?
No. Speaking with a mortgage broker and reviewing options does not impact your credit. A credit check is only completed if you choose to proceed with a pre-approval or application.
Is it better to go to a bank or use a mortgage broker?
A bank can only offer its own products, while a broker compares multiple lenders. Many borrowers choose brokers for broader choice, unbiased advice, and help navigating lender differences.
What matters more, the interest rate or the mortgage terms?
Both are important, but terms often matter more long term. A broker helps evaluate penalties, flexibility, and features alongside the rate to reduce future costs and risks.
Can a mortgage broker help if I’m self-employed?
Yes. Brokers regularly work with lenders that specialize in self-employed and non-traditional income, helping structure applications that reflect true earning ability.
Should I choose a fixed or variable mortgage rate?
It depends on comfort level, cash flow, and long-term plans. A broker explains the pros and cons of each option so the decision is based on strategy, not guesswork.
Can I break my mortgage early if I need to?
Yes, but penalties can vary significantly between lenders. A broker helps explain these differences upfront so you avoid unnecessary costs later.
When is the best time to talk to a mortgage broker?
As early as possible. Speaking with a broker before buying, refinancing, or renewing helps set expectations, uncover options, and avoid surprises.
Contact Us
Have questions about mortgage options, rates, or next steps? Reach out to start a conversation and get clear guidance tailored to your situation.
(604) 612-6252
17674 58th Ave, Surrey British Columbia V3S1L6