Blogs
Reverse Mortgages for Canadian Retirees 55+
Retirement, Reverse Mortgages, Canadian Homeowners 55+
Using a Reverse Mortgage to Build a More Connected, Purposeful Retirement in Canada
Many Canadians 55 and over feel “house rich, cash poor.” Your home may be paid off or close to it, but rising costs can make it hard to keep up with everyday expenses, let alone enjoy hobbies, classes, volunteering, or local travel. A reverse mortgage can be one tool to turn some of that home equity into steady, values‑based support for a more socially connected and meaningful retirement — if it’s used carefully and with eyes wide open to the costs and trade‑offs.
What Is a Reverse Mortgage in Canada, in Plain Language?
A reverse mortgage is a loan secured against your home that lets you access part of your home equity without selling or making regular monthly payments. In Canada, reverse mortgages are regulated products offered mainly by specialized lenders such as HomeEquity Bank and Equitable Bank, and overseen by the Financial Consumer Agency of Canada (FCAC) (canada.ca).
Instead of paying the mortgage down every month, interest is added to your balance. The loan is usually repaid when you move out permanently, sell the home, or the last borrower passes away. Any remaining equity after paying off the loan and costs goes to you or your estate.
Eligibility: Who Can Qualify for a Reverse Mortgage in Canada?
While each lender has its own rules, common Canadian eligibility criteria include (CHIP, Ratehub):
Age: You (and any co‑borrower) must be at least 55 years old.
Primary residence: The property must be in Canada and be your main home, where you live most of the year.
Home equity: You need a meaningful amount of equity (often at least 50% ownership, sometimes more, depending on age and location).
Property type, condition and location: Single‑family homes, condos and some townhomes are often eligible. Rural or unique properties, or homes in poor condition, may qualify for less or not at all.
You do not usually need to pass a traditional income or credit test in the same way as a regular mortgage, but lenders will still review your situation to make sure the reverse mortgage is suitable and that you can keep up with ongoing costs like taxes and insurance.
Homeowner Obligations: What You Must Keep Doing if You Take a Reverse Mortgage
A reverse mortgage is not “free money.” You keep important responsibilities as the homeowner, including (FCAC):
Paying your property taxes on time.
Keeping home insurance in place with adequate coverage.
Maintaining the property in good condition (repairs, safety, basic upkeep).
Continuing to live in the home as your primary residence.
If you fall behind on taxes or let insurance lapse, the lender can treat this as a default. That’s why it’s crucial to build these ongoing costs into your budget before you borrow a dollar of equity.
How the Money Can Support a More Connected, Purposeful Retirement
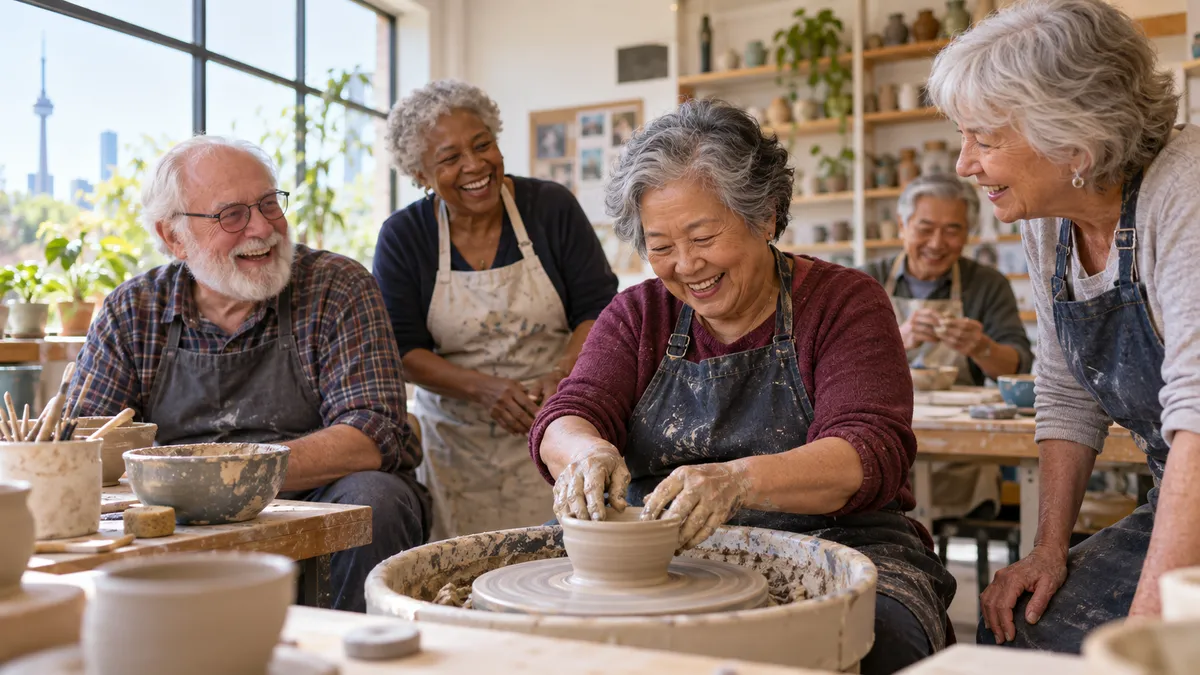
Used thoughtfully, a reverse mortgage can free up a modest, steady stream of cash that supports social connection and purpose — not luxury spending. Many Canadians use the funds to:
Join community classes like art, woodworking, yoga, or language lessons at a local community centre or college.
Cover modest costs for volunteering — transit passes, parking, or supplies for mentoring, coaching youth sports, or helping at a food bank.
Enjoy local travel within your province or nearby regions: visiting grandchildren, taking day trips with friends, or short, simple getaways by train or bus.
Support affordable hobbies such as gardening, music, walking groups, photography or crafting, instead of feeling you must give them up due to rising prices.
Host family and neighbours for simple meals, game nights or holiday gatherings without worrying about every grocery bill.
The goal is not to fund a lavish lifestyle. It is to remove some financial pressure so you can invest in relationships, health and contribution — the things that make retirement feel worthwhile and less lonely.
Costs, Fees and the Impact of Compounding Interest on Your Equity
Reverse mortgage interest rates in Canada are typically higher than conventional mortgage rates, because lenders are taking on more risk and waiting many years to be repaid (rates.ca). On top of interest, you can expect:
Set‑up costs: Appraisal, legal fees and administrative charges that often total in the range of several thousand dollars, depending on the lender and province (FCAC).
Ongoing fees: Some products include annual administration or servicing fees, which should be clearly disclosed in writing.
Prepayment penalties: There may be a cost if you choose to pay off the loan early, for example if you sell the home sooner than expected. Ask for details and examples in dollars, not just percentages.
Because you are not making regular payments, interest compounds. This means you pay interest on the interest that was added in previous months or years. Over time, the balance can grow quickly, especially if you borrow a large amount or keep the loan for many years. The result is reduced future equity for you and your estate.
Most major Canadian providers offer a “no negative equity guarantee,” which means you or your estate should not owe more than the fair market value of the home when it is sold, as long as you meet your obligations. Still, it is important to understand that a reverse mortgage will almost always mean less inheritance for your heirs compared with not borrowing at all.
📌 Key takeaway: A reverse mortgage trades some of your future home equity for cash you can use today. The question is whether that trade supports the retirement you value most.
Setting a Responsible, Values‑Based Budget for Reverse Mortgage Funds
Before signing anything, decide how much you truly need — not how much you are offered. Many lenders will approve you for more than you actually require to live well and stay connected. A simple approach is:
List your basic expenses: housing costs, food, utilities, medications, transportation and insurance. Make sure these are covered by pensions, CPP/OAS, savings and other secure income first, whenever possible.
Identify connection and purpose expenses: community classes, club memberships, transit to visit friends or volunteer roles, modest trips, and small hospitality costs for family gatherings.
Decide what you can comfortably fund from existing income, and where there is a genuine gap that a reverse mortgage could fill without encouraging overspending.
Choose a smaller initial borrowing amount and keep some equity in reserve. You can often draw additional funds later if needed, rather than taking the maximum up front.
💡 Pro tip: Treat your reverse mortgage like a carefully drawn‑down savings account, not a windfall. Direct the money toward experiences and relationships that truly matter to you.
Alternatives to Consider Before You Tap Home Equity
A responsible decision includes looking at other options. Depending on your situation, you might explore:
Government and community programs: Many cities and provinces offer low‑cost or subsidized seniors’ programs, fitness passes, classes and transit discounts. These can reduce the need to borrow at all.
Budget review and debt consolidation: Sometimes a careful look at spending, combined with paying off high‑interest credit cards using a smaller home equity line of credit (HELOC), can relieve cash‑flow pressure at a lower cost than a reverse mortgage. A HELOC, however, does require regular payments and credit approval.
Downsizing or right‑sizing: Moving to a smaller or more accessible home, or to a different community, can free up equity and reduce monthly bills. This can be disruptive, but for some it also creates new social opportunities in a building or community geared to older adults.
Renting out a room or suite: If your home layout allows, a tenant or homeshare arrangement can bring in income and, if chosen carefully, extra companionship. This option does come with responsibilities as a landlord or host.
If, after exploring these paths, a reverse mortgage still feels like the best fit, you can move forward knowing you have done your homework and are choosing it — not falling into it — out of pressure or fear.
Having Calm, Honest Family Conversations About Your Decision
A reverse mortgage affects not just you, but also your partner and, often, your adult children or other heirs. It can be helpful to sit down together and explain:
Why you are considering it — for example, to stay in your home, stay involved in your community, and avoid feeling isolated due to money worries.
How much you plan to borrow and how the funds will be used, focusing on modest, meaningful goals rather than big‑ticket purchases.
The expected impact on their future inheritance, so there are no surprises later on.
Invite questions and listen to concerns. You may not all agree, and that is okay. Ultimately, it is your home and your retirement. But open conversation can prevent hurt feelings and misunderstandings, and sometimes family members may suggest other ways to support you — such as shared housing, help with repairs, or joint budgeting — that reduce the need to borrow as much.
A Practical Decision Checklist for Canadian Homeowners 55+
Use this checklist to slow the process down and make a grounded, confident choice:
Have I clearly listed my goals for retirement — social, emotional, and financial — not just my debts and bills?
Have I explored alternatives like government programs, budgeting help, downsizing, or a HELOC with regular payments?
Do I understand the total costs — interest, fees, and potential penalties — in dollar terms over time, not just in percentages?
Have I spoken with an independent financial planner or counsellor who does not earn a commission from reverse mortgages?
Have I had an open conversation with my family or anyone who may be affected by a smaller estate?
Am I borrowing only what I truly need, in a way that supports my values and wellbeing?
Smart Questions to Ask a Reverse Mortgage Broker or Lender
When you speak with a broker or lender, you are interviewing them as much as they are assessing you. Here are questions that can help keep the conversation balanced and transparent:
“Can you walk me through all fees and costs I’ll pay at the start, during the loan, and if I repay early — in dollars, not just percentages?”
“How will my loan balance grow over time if I borrow this amount and keep it for 5, 10, or 15 years? Can you show me written examples?”
“What are my ongoing obligations around taxes, insurance and maintenance, and what happens if I fall behind?”
“Is there a no negative equity guarantee, and what are the conditions?”
“How are you paid, and do you receive higher compensation for certain products or loan sizes?”
💡 Pro tip: Take notes, ask for everything in writing, and never feel rushed. A reputable professional will welcome your questions and your pace.
Frequently Asked Questions About Reverse Mortgages and Socially Connected Retirement
Will I still own my home?
Yes. You remain the homeowner and stay on title. The lender has a registered charge against your home, similar to a regular mortgage. You must keep living there as your primary residence and meet your obligations.
Can I lose my home?
As long as you meet the terms of your agreement — paying property taxes, keeping insurance, maintaining the home and living in it — it is uncommon for a reverse mortgage to lead to forced sale. Problems usually arise when those obligations are not met, which is why budgeting is so important (FCAC).
Will a reverse mortgage affect my government benefits?
Reverse mortgage funds are loan proceeds, not income, so they typically do not affect Old Age Security (OAS) or Canada Pension Plan (CPP). However, they could affect income‑tested benefits if the funds increase your investment income or savings. It is wise to check with Service Canada or a financial professional about your specific situation.
Can I use the money for anything?
In most cases, yes. There are no strict rules on how you spend the funds. The real question is how to use them in a way that supports your long‑term wellbeing — paying off high‑interest debt, making the home safer, and investing in community and purpose, rather than impulsive big‑ticket purchases.
What happens when I pass away?
When the last borrower dies or moves into long‑term care, the loan usually becomes due. Your estate or family can choose to sell the home to repay the balance, or pay it out from other funds if they wish to keep the property. Any remaining equity after the loan and costs are paid stays with your estate.
A No‑Pressure Invitation from Rossander: Explore Your Options, at Your Pace
If you are a Canadian homeowner 55+ wondering whether a reverse mortgage could help you stay in your home, stay active in your community and enjoy a more connected, purposeful retirement, you do not have to figure it out alone — and you should never feel rushed into a decision.
At Rossander, our role is to listen first: to your worries, your hopes, and the kind of life you want your retirement years to support. From there, we can walk you through reverse mortgages alongside other options, explain the numbers in plain Canadian English, and help you decide whether borrowing against your home fits your values and long‑term plans.
There is no obligation to move forward, and no expectation that a reverse mortgage will be the answer for everyone. Sometimes the best outcome of a conversation is the peace of mind that comes from knowing you have explored your choices carefully and on your own terms.
If you are ready for a calm, straightforward discussion — with plenty of time for questions — reach out to Rossander when it feels right for you. Your home, your equity and your retirement deserve nothing less than a thoughtful, pressure‑free approach.

Frequently Asked Questions
Do mortgage brokers actually get better rates?
Often, yes. Brokers have access to rates from multiple lenders, including some not available directly to consumers, and can compare them to find competitive options for your situation.
Will talking to a mortgage broker hurt my credit score?
No. Speaking with a mortgage broker and reviewing options does not impact your credit. A credit check is only completed if you choose to proceed with a pre-approval or application.
Is it better to go to a bank or use a mortgage broker?
A bank can only offer its own products, while a broker compares multiple lenders. Many borrowers choose brokers for broader choice, unbiased advice, and help navigating lender differences.
What matters more, the interest rate or the mortgage terms?
Both are important, but terms often matter more long term. A broker helps evaluate penalties, flexibility, and features alongside the rate to reduce future costs and risks.
Can a mortgage broker help if I’m self-employed?
Yes. Brokers regularly work with lenders that specialize in self-employed and non-traditional income, helping structure applications that reflect true earning ability.
Should I choose a fixed or variable mortgage rate?
It depends on comfort level, cash flow, and long-term plans. A broker explains the pros and cons of each option so the decision is based on strategy, not guesswork.
Can I break my mortgage early if I need to?
Yes, but penalties can vary significantly between lenders. A broker helps explain these differences upfront so you avoid unnecessary costs later.
When is the best time to talk to a mortgage broker?
As early as possible. Speaking with a broker before buying, refinancing, or renewing helps set expectations, uncover options, and avoid surprises.
Contact Us
Have questions about mortgage options, rates, or next steps? Reach out to start a conversation and get clear guidance tailored to your situation.
(604) 612-6252
17674 58th Ave, Surrey British Columbia V3S1L6